Asset Management Operational - Acquisition and Disposal Policy
Purpose
Effective asset management and capital expenditure are essential for the continuity, development, and growth of Otago Polytechnic.
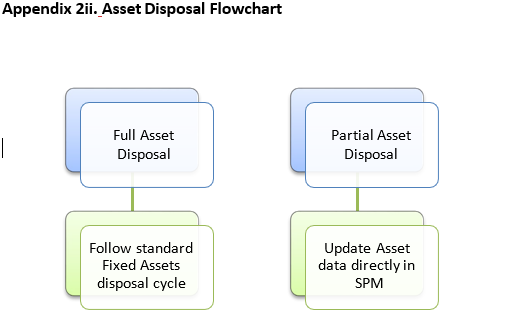
The purpose of this policy is to ensure that capital expenditure by Otago Polytechnic is planned, evaluated, authorised, implemented, monitored, and reported in a systematic manner, for best practice, and that the disposal of assets is a transparent process that achieves best value for Otago Polytechnic. A flowchart of the process is attached to the Standard Operating Procedure (SOP) (refer to Appendix 2ii).
Compliance
Education and Training Act 2020 and
Education and Training Amendment Act 2021
Public Finance Act 1989, and all subsequent amendments
Public Records Act 2005, and all subsequent amendments
Operational and Financial Parameters (OFP) (NZIST)
Policy Definitions
Definitions
Assets can be defined by their nature and include:
- Fixed assets (capitalised assets including electronic resources).
- Work in
Other assets not covered in this policy being:
- Intangible
- Current
Intangible assets i.e., non-physical assets such as goodwill, course development, patents, and other intellectual property.
Current assets i.e., assets that have an initial economic life of less than one (1) year or are able to be realised within one (1) year.
A capitalised asset:
- Is an item that has an estimated useful life in excess of one (1)
- Has a cost that satisfies the capitalisation
- Has not been acquired or constructed with the intention of resale; and
- May include such expenditure incurred on an existing asset to improve its functionality and/or extend its useful life but not merely reinstate the future economic benefit of an asset (i.e., repairs and maintenance).
The fixed asset register is the schedule of fixed assets maintained by the Financial Services and is used for financial reporting purposes.
The SPM asset management system (SPM) provides condition assessment data, used for strategic decision-making in regard to acquisition, repair, and disposal of assets. The SPM system is maintained by the delegated SPM administrator.
The capitalisation threshold for the fixed asset register is $2000 excluding GST and applies to:
- Individual
- A collection of related items or components that cannot operate in isolation, whose combined original cost exceeds the threshold
- An accessory which is acquired for permanent attachment to an existing capitalised asset. The cost of the accessory is to be added to the existing asset if it meets any of the capitalisation thresholds.
- Pooled assets of a similar type, whose combined cost exceeds the threshold.
The capitalisation threshold for the SPM asset management system is $2000 excluding GST.
Disposal of assets - the sale or partial sale, scrapping, write-off, barter, trading, or any other means of ceasing beneficial ownership or custody of assets.
Policy
Purchase of Assets (refer to Appendix 2i and 2iii.).
1.1All purchases of assets should be included in the current capital expenditure budget or reforecast approved by Te Pūkenga Council. Delegations Policy policy sets out the circumstances and procedures whereby unbudgeted assets can be purchased (only allowed if approved by the Deputy Executive Director: Operations prior to the purchase being made).
1.2.Purchases must be made in accordance with the Procurement Policy and Procurement and Purchasing Policy .
1.3All approved fixed asset (capital) purchases must have a five-digit Capital Approval Number (CAN), assigned by either the Financial Services, Information Systems and Support (ISS) or Campus Services.
1.3.1The CAN number is used for the analysis code part of the account number, on the items purchase order. Once the purchase order is approved and physically received the order must be receipted in Finance One. After the purchase is receipted, an Asset Additions Form must be completed (refer to Appendix 2iii)) and sent to Financial Services.
1.4.Finance will:
1.4.1Load the asset into the Fixed Asset Register.
1.4.2Assess if the asset needs to be loaded into the SPM Capital Asset Management System (land and buildings, and teaching assets greater than $2000).
1.4.3Contact the College/Service Area to obtain the additional information required for the SPM system.
1.4.4Forward the details to the SPM administrator for them to be entered.
1.5All assets must have a barcode number allocated (generally by Financial Services) and forwarded to the College/Service Area for attachment to the asset. The exception is assets purchased by ISS and Campus Services who allocate their own barcode number and advise Financial Services. The barcode number becomes the unique identifier for the life of the asset.
1.6If the asset purchased replaces an existing asset, the existing asset must be disposed of in line with the following disposal of assets procedures. Refer to Appendices 2ii and 2iv).
2 Disposal of Assets (refer to Appendix 1ii and Appendices 2ii and 2iv).
2.1Assets may be disposed of for these reasons:
Surplus to current or immediately foreseeable requirements.
Part of an asset replacement programme.
Unserviceable or beyond economical repair.
Technologically obsolete and operationally inefficient.
A replacement asset has been purchased.
2.2All monies received from the disposal of assets must be banked into Otago Polytechnic bank account as soon as is practicable (Education and Training Act 2020 and the Education and Training Amendment Act 2021).
2.3Otago Polytechnic has delegated authority to dispose of assets up to a certain financial limit (currently $50,000). Assets with values above this limit require written consent from the Secretary of Education to:
Sell or dispose of assets or interests in assets.
Mortgage or change assets or interests in assets.
Grant leases of land or buildings.
2.4Disposal of assets will be carefully managed to ensure the best net value for the asset is realised and completed in an efficient, effective, and transparent manner. All disposals will be appropriately authorised and adequately documented.
The sale price can be either book value or market value as approved by the Director: Financial Service, the Digital Director: Digital, or the Deputy Executive Director: Operations.
2.5IT Fixed Assets will not be sold or gifted to employees or recently departed employees of Otago Polytechnic.
2.6.All Otago Polytechnic owned fixed assets will be returned to Otago Polytechnic on termination of their employment with Otago Polytechnic.
3. Recording of Assets
3.1All assets that exceed the capitalisation threshold (refer to Definitions above) must be recorded on the fixed asset register by the Financial Services and in the SPM system by the delegated SPM administrator in accordance with the SOP, flowcharts, and forms (refer to Appendices 1 and 2).
3.2Assets are recorded in the fixed asset register for finance purposes and in the SPM asset management system for strategic asset management purposes.
3.3In the fixed asset register, purchased assets are initially recorded at cost price with the exception of donated items which are recorded at their fair market value.
3.4After the initial purchase, assets are recorded at cost price less depreciation or at revaluation dependent on the asset class.
4. Asset Stocktake
Physical verification of assets is to be completed in line with the following procedures:
4.1Colleges and Service Areas are primarily responsible for undertaking verification (stocktake) of their assets and specified items (except for land and buildings). This verification process is to be completed annually.
4.2Financial Services is responsible for undertaking verification of specified items (except for land and buildings). This verification process is to cover:
Annual physical verification of assets with a net book value over $50,000.00.
Bi-annual physical verification of assets with net book value between $20,000 and $49,999.99.
Tri-annual verification of assets with net book value between $2,000 and $19,000.00.
Assets with a net book value below $2,000 will not be subject to asset verification.
4.3The objective of physical verification is to maintain the integrity of the Otago Polytechnic’s Asset Register by:
Ensuring that all assets held with a net book value over $2,000 are recorded in the register
Verifying that all assets in the register with a net book value over $2,000 have been physically located and are still functional and in use; and
Updating the register for unrecorded changes in asset ownership, responsibility, or location.
References
Policies
Delegations Policy and Delegations Register
Reference Documents - attached below:
Appendix 1. Standard Operating Procedure
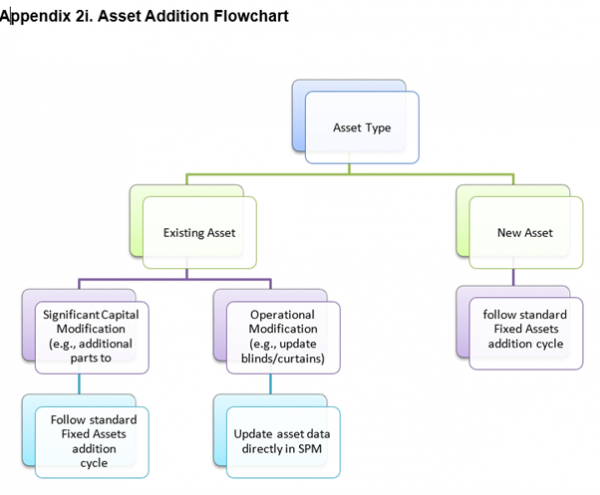
Appendix 2.i Asset Addition Flowchart
Appendix 2.ii Asset Disposal Flowchart
Appendix 2.iii Asset Additions Form
Appendix 2.iv Disposal of Assets Form
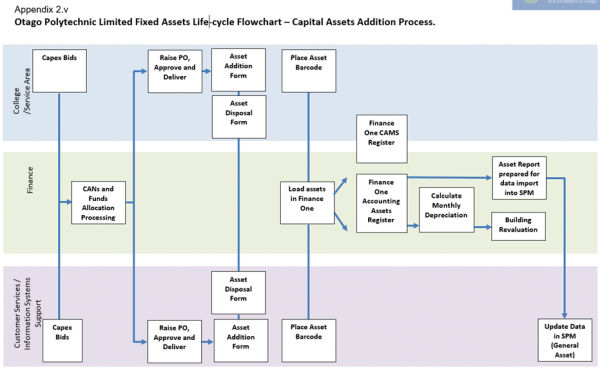
Appendix 2.v. Fixed Assets Lifecycle Flowchart – Capital Assets Addition Process.
Approved
APPROVED:
Dr. Megan Pōtiki
Executive Director
Date: 5/5/2025
POLICY VERSION V4: Previously Coded: MP0438
Appendix 1 Standard Operating Procedures
In relation to policy Asset Management Operational - Acquisition and Disposal Policy the following procedures should be followed, for disposal of assets.
ISS Assets:
- The asset user must email ISS to organise the appropriate disposal or relocation of the asset. ISS must follow the standard asset disposal procedures.
Non-ISS Assets:
- If the asset is still in good working order the College/Service Area should contact the CEnvt who will assess whether it is appropriate to offer to other Otago Polytechnic Limited Colleges/Service Areas for use.
All Disposals:
- The following process is followed:
- Colleges/Service Area should ensure that all assets being disposed of do not contain any software, Otago Polytechnic Limited information, or logos.
- A request for disposal is made by the completion of the Disposal of Assets Form (Appendix 2iv) by the Head of College/Director: ISS or CEnvt (excluding the actual sale price and the purchaser sections).
- The partially completed form should be forwarded to Financial Services for appropriate sign-off. Completion and signing of the Disposal of Assets Form by all parties will satisfy the appropriate delegated authority requirements.
- Financial Services will return the signed form to the Head of College/Director: ISS or CEnvt.
- If the asset has a market value or a book value greater than $20,000 Financial Services must forward the form to the DCE: Corporate Services to approve the sale and to agree the method of sale.
- Once the form is signed the listed asset is able to be disposed of for no less than the approved sale price.
- Once the assets have been sold the Head of College/Director: ISS or CEnvt must complete the section of the form advising the sale proceeds and the purchaser for each item number listed.
- The barcode must be removed and returned to Financial Services with the fully completed disposal of assets form.
Method of Sale (Estimated Market Value) Guidelines
- The Asset Owner must establish the estimated market value based on previous sales, from advertisements or other sources such as newspapers and internet auctions. Where no market value is available the written down value from the fixed asset register should be used as a best estimate. It is essential that the process whereby the market value is estimated be properly documented, including keeping copies of relevant advertisements. This documentation should be attached to the Disposal of Assets Form. In many cases, a sale using Trade Me will be appropriate, with the reserve set at the approved sale The Otago Polytechnic Limited Trade Me account should be used (details can be obtained from Financial Services).
- The Head of College/Director: ISS or CEnvt are responsible for ensuring an arm's length transaction between the seller and the buyer and approving the sale in writing.
- Transportation costs are to be met by the buyer and the purchase is at the buyer’s risk.
- Offers received must be documented and the Head of College/Director: ISS or CEnvt must approve the successful ofer.
Sale of Land and Buildings:
- Any sale of land or buildings regardless of ownership or value must be approved by the Secretary of Education via the Otago Polytechnic Limited Board. The DCE: Corporate Services will ensure that internal and external delegations and approval processes are followed.
Trade-in of Assets:
- Where the trade-in of an existing asset is included in the acquisition of a new asset, the external requisition and purchase order must identify:
- The asset being acquired, including full cost.
- The asset being traded in with full details of the trade-in value.
- The net amount payable.
Donations to Schools, Charities, or Non-profit Organisations.
- Surplus assets may be donated to charities, schools or colleges, or community/non-profit organisations.
- The reasons for a donation rather than a sale must be included on the Assets Disposal Form. In most cases, it is expected that the asset will have been previously offered for sale however no acceptable offers were received.
- CEnvt can assist with transporting the item to the organisation with any costs being met by the College Service Area.
- Items cannot be given/donated to staff or learners unless approved by the Chief Executive or DCE: Corporate Services.
Obsolete Unserviceable or Beyond Economical Repair Assets that cannot be sold.
- Assets or groups of assets that are obsolete, unserviceable, or beyond economical repair and cannot be sold or donated to a community organisation must be written off.
- CEnvt must be contacted for assistance with regard to items with environmental obligations.
Appendix 2.i Asset Addition Flowchart
Appendix 2.ii Asset Disposal Flowchart
Appendix 2.iii Asset Additions Form
Appendix 2.iv Disposal of Assets Form
Appendix 2.v. Otago Polytechnic Fixed Assets Life-cycle Flowchart – Capital Assets Addition Process.